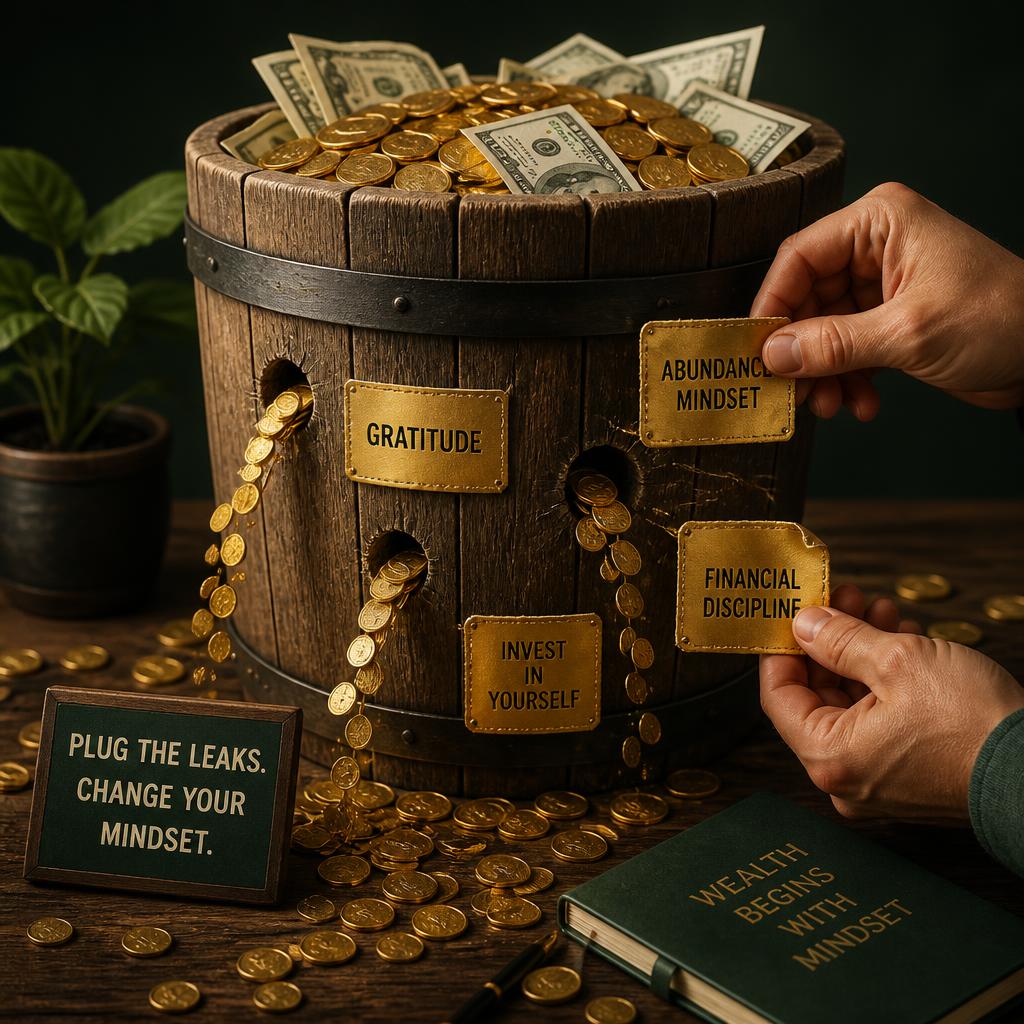
You Cannot Out-Earn a Leaking Bucket
Every household has silent outflows — small, automatic, and quietly forgotten. They feel too minor to bother with, which is exactly why they survive for years untouched. A $12.99 subscription you forgot about, a $9 fee for an account you barely use, an insurance policy you have never once compared to another quote — none of them feel worth the hassle individually. Stacked together across a household, they routinely add up to hundreds of dollars a month that could otherwise be wiping out a debt.
This is why a genuine sweep, done properly and once, tends to outperform a raise. A pay rise of $300 a month is taxed, delayed, and often absorbed into a slightly nicer lifestyle before it ever reaches the debt. Three hundred dollars found in your existing spending is available today, tax-free, and already has a habit of being redirected because you deliberately went looking for it.
Do this sweep once, properly, with your last three months of bank statements open in front of you, and you will pay for the hour it takes many times over.
The Seven-Point Sweep
1. THE SUBSCRIPTION AUDIT
Open your bank and card statements for the last three months. Highlight every recurring charge — streaming, apps, gym, cloud storage, software, memberships, insurance add-ons, extended warranties. Cancel anything you have not deliberately used in the past 30 days. The average household finds $80–$200 a month here, and it takes about half an hour.
2. Ask for a lower interest rate
Phone your card issuer and say plainly: "I've been a customer for X years, I'm getting offers at a lower rate, can you reduce my APR?" A meaningful share of callers get a reduction on the spot. Ten minutes for a rate cut is the best hourly rate you will ever earn.
3. Re-shop every insurance policy annually
Car, home, contents, health, phone — loyalty is punished, not rewarded, in almost every insurance market. Get three quotes and take the best one back to your current insurer before you switch. Typical saving: $300–$900 a year for ten minutes of admin.
4. Attack the food bill intelligently
Not by eating badly, but by planning — a weekly menu, one shop, a written list, no shopping while hungry, and cooking double portions for the freezer. Food delivery apps are usually the single largest discretionary leak in a modern household budget, often unnoticed because each order feels small on its own.
5. Kill the fees
Account keeping fees, ATM fees, late fees, overdraft fees, foreign transaction fees, paper statement fees — banks earn billions from customer inertia. Switch to a fee-free everyday account and automate every minimum payment so a late fee can never happen again.
6. Downgrade temporarily, not forever
This is a season, not a life sentence. Phone plan, car, holiday, gym membership — each downgraded for eighteen months redirects thousands of dollars at the debt, and every one of them can be upgraded again the day you are free.
7. Sell What You Are Storing, Not Using
The unused bike hanging in the garage. The second TV in a spare room. The tools from a project finished years ago, the old console, the handbag that never left its box. Most homes contain somewhere between $1,000 and $3,000 of genuine resale value sitting quietly in cupboards. That money alone can wipe out your smallest debt this month and give the rest of your plan real momentum.
Set a firm date — this weekend, not "eventually" — walk through every room with a bag, and list anything unused for a year straight to a local marketplace. Momentum from one good decluttering weekend often carries into the rest of the plan too.
What the sweep looks like added up
Subscriptions cancelled: $140/month. Insurance re-shopped: $50/month. Interest rate cut saving: $35/month. Food bill trimmed: $120/month. Two items sold: $650 one-off. That is $345 a month ongoing, plus a $650 lump sum — enough to seriously accelerate almost any debt snowball or avalanche.
You do not need a second job to find $300 a month. You need one honest afternoon with your bank statements.
The money was already there — it just wasn't aimed at anything
Make the Sweep a Quarterly Habit
Subscriptions creep back in. Insurance premiums rise quietly at renewal if you don't check. A new fee gets introduced somewhere and nobody notices for eight months. Put a recurring reminder in your calendar every three months to repeat steps one, two and three — the biggest three wins — in about twenty minutes. It is far easier to maintain a leak-free budget than to find all the leaks again from scratch each time.
Now Aim It
Whatever you free up, redirect it automatically on the day you get paid, into the target debt from your payoff method. Money that stays sitting in the everyday account has a habit of getting spent on something forgettable. Money that moves the moment it lands gets used for the job you actually assigned it.
This week's sweep checklist
- Highlight every recurring charge on three months of statements.
- Call your card issuer and ask for a lower rate.
- Get three insurance quotes and take the best one back to your insurer.
- Plan one week of meals before you shop, and shop once.
- Check your account for hidden fees and switch if needed.
- Sell two unused items this weekend.
Where should I start if I only have twenty minutes?
The subscription audit. It is the fastest, highest-value step and usually finds the most money for the least effort.
Will cancelling subscriptions actually make a difference?
Individually, no single one feels significant. Combined across a household, they routinely total $80–$200 a month — real, ongoing money once redirected to debt.
What if my insurer won't match a cheaper quote?
Switch. Loyalty rarely earns a discount in insurance, and the admin of switching usually takes less than an hour for a saving that repeats every single year.
Isn't downgrading things embarrassing?
Nobody is tracking your gym membership or your phone plan except you. A temporary downgrade while you clear debt is a strategy, not a failure, and it is completely reversible the day your goal is met.
The short version
- 01Small recurring leaks add up to $300–$700 a month in most households.
- 02The subscription audit is the fastest, highest-value place to start.
- 03Re-shopping insurance and asking for a lower interest rate cost nothing but a phone call.
- 04Selling unused items can produce a genuine lump sum this weekend.
- 05Redirect everything you free up automatically to your target debt on payday.
Once the leaks are plugged, route the freed-up cash through the three-account budget, protect it with an emergency fund, and choose the order to knock out your balances in Snowball vs Avalanche.