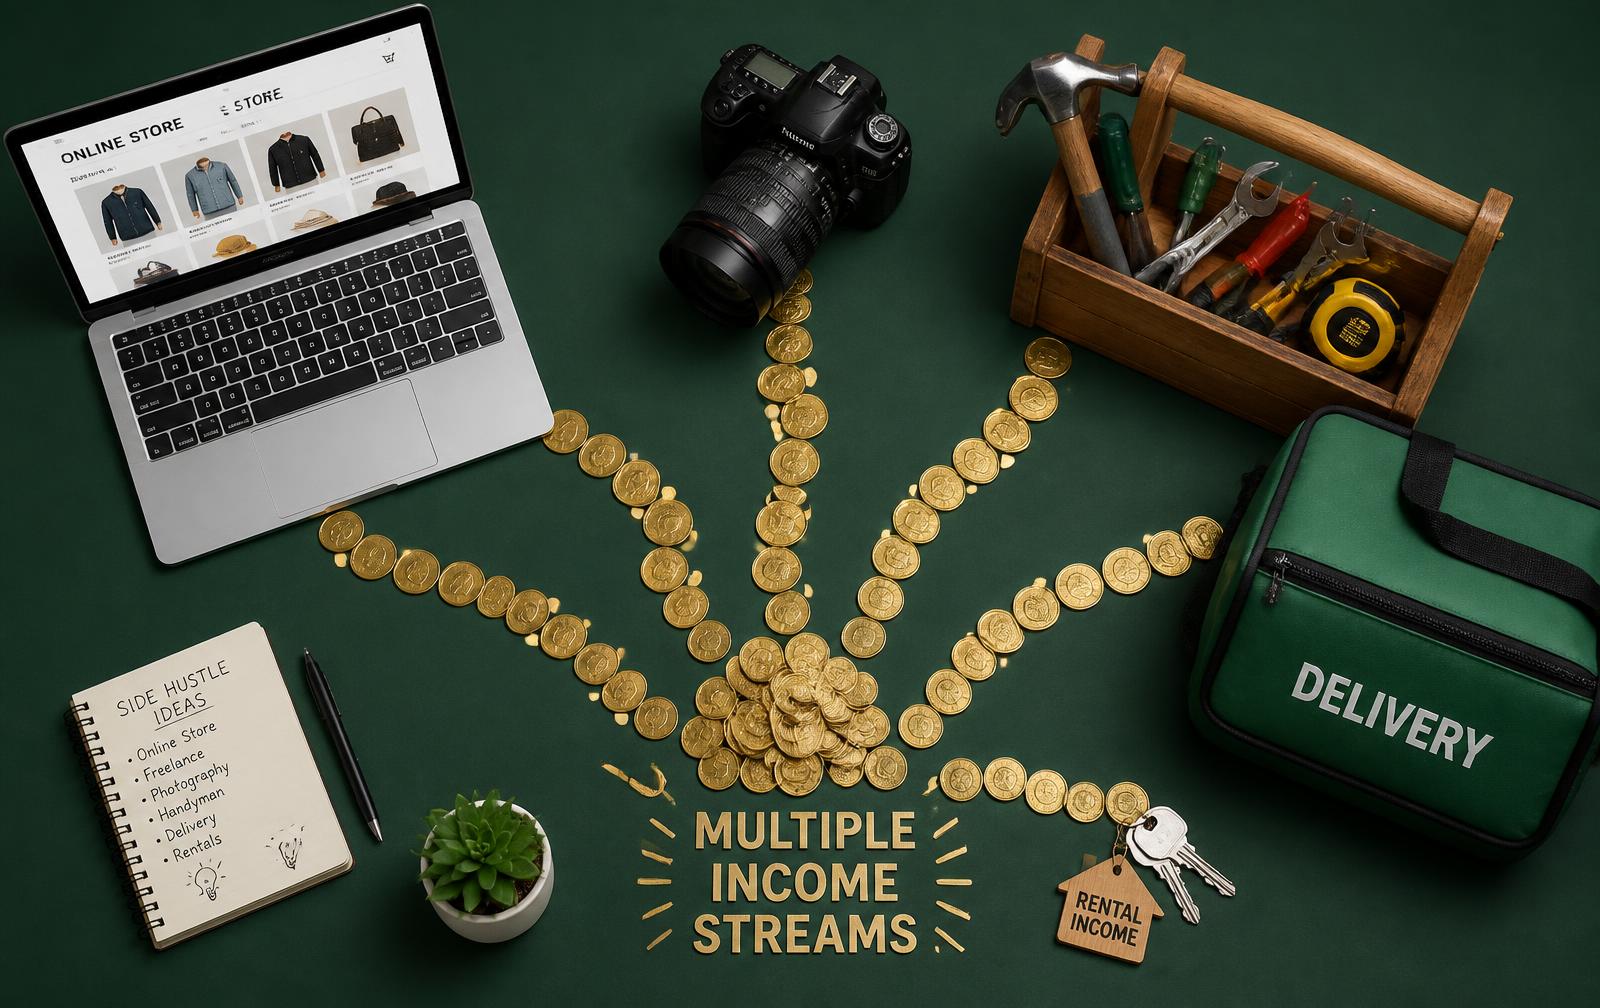
Fast Money First, Scalable Money Second
When you are in debt, speed matters more than elegance. Start with something that pays within two weeks, then use that early momentum — and the confidence it brings — to build something that pays while you sleep. Do not start with the clever idea; start with the paid one, and let the clever one grow alongside it once the pressure has eased.
Below are twelve realistic streams grouped by how quickly they turn into cash in your account, followed by how you choose just one to actually commit to, because trying all twelve at once is the fastest way to finish none of them.
Pays Within Two Weeks
- Sell what you own. Marketplace, classifieds, local groups. Most homes hold $1,000–$3,000 of unused value in tools, electronics, furniture and clothing.
- Delivery and rideshare. No interview, immediate pay, total flexibility around your existing job. Watch the vehicle running costs closely.
- Local services. Cleaning, lawns, pressure washing, moving help, furniture assembly, pet sitting — all bookable within days through local groups or apps.
- Weekend hospitality or retail. Unglamorous, reliable, and it stacks fast because the pay cycle is short and predictable.
Pays Within Two Months
- Freelancing your work skill. Bookkeeping, admin, design, copywriting, video editing, spreadsheets, IT support — sold to small businesses who need it occasionally.
- Tutoring. School subjects, music, languages, software. Strong hourly rates and repeat clients once word gets around.
- Trades and repairs. Bikes, phones, furniture restoration, small electrical or handyman work where you are qualified and insured.
- Renting what you own. A spare room, parking space, trailer, tools, camera gear or storage space — assets that earn while idle.
Builds Over Six to Twelve Months
- An online store. Print-on-demand, handmade goods, or a narrow niche you genuinely understand well enough to source and market.
- Digital products. Templates, courses, presets, guides — made once, sold repeatedly, with almost no ongoing cost per sale.
- Content with an audience. Slow to start, but a small loyal audience monetises reliably once trust is built.
- Investing. Worth exploring only after high-interest debt is gone — you cannot reliably out-earn a 22% card through investment returns.
| Stream | Speed to first dollar | Effort to sustain |
|---|---|---|
| Selling unused items | Days | One-off, low |
| Delivery / rideshare | Days | Ongoing, moderate |
| Local services | 1–2 weeks | Ongoing, moderate |
| Freelancing a work skill | 2–4 weeks | Ongoing, flexible |
| Tutoring | 2–6 weeks | Ongoing, steady |
| Renting an asset | 2–6 weeks | Low, passive |
| Digital products | 3–6 months | High upfront, then low |
How To Choose Just One
Pick the option with the shortest distance between your existing skills and someone else's existing problem. Give it 90 focused days before judging it. Three abandoned side hustles earn exactly nothing; one boring, persistent one earns real money. If you genuinely cannot decide, default to whichever option pays fastest — cash flow now beats a perfect plan on paper.
Chasing five streams at once
It is tempting to list a marketplace item, sign up for delivery driving, pitch a freelance client and open an online store in the same weekend. Energy spread across five half-started streams usually produces less than energy focused on one. Start narrow, prove it works, then expand.
I sold my old camera gear in a weekend and used the money to open the "extra income" account. Six months later that same account had freelance payments landing in it every fortnight.
A reader's note, paraphrased
Keep it clean
- Separate bank account for the new income, kept apart from everyday spending.
- Set aside 25–30% for tax from day one, even if it feels premature.
- Track hours honestly so you know your true hourly rate, not just the headline fee.
- Never fund a side hustle with new debt — start with what you already own.
- Send 100% of the profit to the debt until it is gone, then redirect it to savings.
Which income stream should I start with if I have no savings at all?
How much time should a side income realistically take?
What if my side hustle isn't making much after a few months?
Should I incorporate a business for a small side income?
Is it worth borrowing to start a side hustle?
The short version
- 01Start with the fastest-paying option, not the cleverest one.
- 02Twelve options exist across three speed tiers — pick from the fastest tier first.
- 03Commit to one stream for 90 days before judging or switching.
- 04Keep a separate account, set aside tax, and never borrow to start a side hustle.
- 05Send all early profit to debt, then redirect it to savings once debt-free.
Combine this with the raise and skill-selling strategies on grow your income and the savings from cut your debts, and the plan stops taking years and starts taking months. When you're ready to map the whole route, see the debt-free plan.