The Complete Sequence
The Debt Escape Plan
Getting out of debt is a story with an order to it. Skip a chapter and you end up back at the beginning. Here are the six stages, in sequence, with the tools to work each one.
Stage One
Why Are You In So Much Debt?
Nobody borrows their way into trouble on purpose. The balances arrive one reasonable decision at a time — a card for the emergency, a loan for the car, a repayment holiday that quietly capitalised. By the time the total is frightening, the original cause has been forgotten.
Find the cause first. An income gap needs a different rescue to lifestyle creep. A medical shock needs hardship support, not a snowball spreadsheet. One crushing asset needs a decision, not discipline. Everything that follows on this page depends on answering this question truthfully.
Stage One Tool
Why Am I In This Much Debt?
Tick everything that is true. Honesty here decides the whole plan.
Stage Two
Put Every Debt On One Page, Then Rank It
Write down every balance, every rate, every minimum. Include the ones you avoid thinking about — the family loan, the tax bill, the buy-now-pay-later. The total will be worse than the number in your head, and that is exactly the point: a real number can be attacked, a vague dread cannot.
Then rank them. Avalanche puts the highest interest rate first and costs you the least money. Snowball puts the smallest balance first and gives you the fastest win. The calculator below runs both on your actual numbers, so you can choose with evidence instead of opinion.
Interactive Tool
The Payoff Order Calculator
Enter your real numbers. Nothing is sent anywhere — this runs entirely in your browser.
Total owed $25,700 · minimums $670/mo
Avalanche — highest rate first
3y 0m
Interest paid $5,457
Order: Credit card → Personal loan → Car loan
Snowball — smallest balance first
3y 1m
Interest paid $5,740
Order: Personal loan → Credit card → Car loan
That extra $200 a month cuts 17 months and saves $3,809 in interest.
Stage Three — cut the rate before you cut the balance
Most people start paying extra before they have done the cheapest thing available: making the debt cost less. A rate-reduction phone call takes twenty minutes. A 0% balance transfer can freeze interest for a year and a half. A consolidation loan can turn five scattered repayments into one lower one. Do this before Stage Four and every dollar afterwards works harder.
Stage Four
The One Debt That Dwarfs The Rest
For most households in serious trouble, one item is responsible for the majority of the problem: the mortgage, the car loan, the boat, the caravan, the investment that turned. You have exactly four honest options. Pick one deliberately — refusing to choose is choosing the slowest one.
PAY IT DOWN HARD
Choose it when:
Watch for: Slowest route. Only works if income comfortably covers everything else.
REFINANCE OR CONSOLIDATE
Choose it when:
Watch for: A longer term can cost more overall. Compare total interest, not the monthly figure.
DOWNSIZE THE ASSET
Choose it when:
Watch for: Transaction costs. Run them before you commit.
SELL IT OUTRIGHT
Choose it when:
Watch for: Emotionally hard, financially decisive. Most debt-free stories contain exactly one sale like this.
The Honest Test
Would you buy this asset again, today, at this repayment?
If the answer is no, you are not keeping it for financial reasons — you are keeping it because selling feels like failure. It isn't. Selling one asset is the single most common turning point in every debt-free story we have collected.
Stage Five
Out-Earn The Problem
There is a floor to cutting costs — you cannot spend less than nothing on groceries. There is no ceiling on earning. Once the rate is cut and the big debt is decided, the fastest remaining lever is more money coming in.
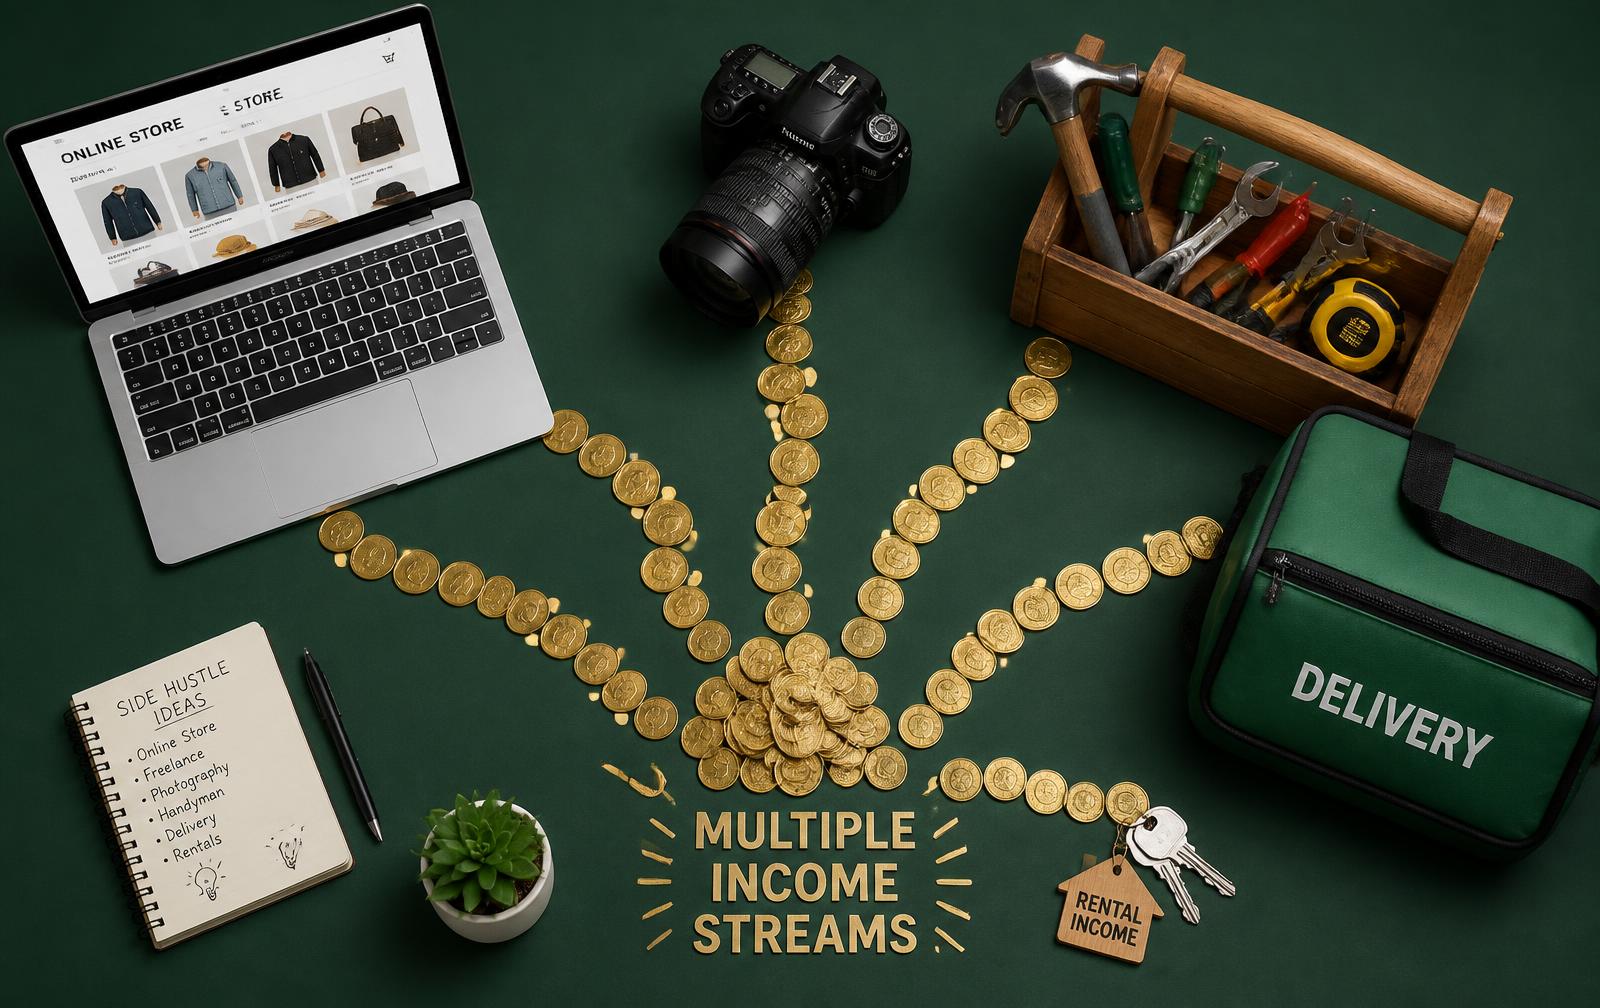
- Raise your rate where you already work — a pay review is the cheapest income stream that exists.
- Sell the dormant assets — the unused gear in the garage is often a month of repayments.
- Add one repeatable side income — freelancing a skill, weekend trade work, tutoring, delivery, resale.
- Ring-fence every extra dollar — new income that lands in the everyday account disappears.
Stage Six
Lock The Door Behind You
The month the last debt clears is the most dangerous month of the whole plan. You have a large repayment suddenly free and a year of self-denial behind you. Redirect it before it redirects itself: three to six months of expenses in a separate account, then investing.
And keep the inner work going. The balances were built by decisions, and decisions are made by a mind. That is why this site carries meditation, prayer and manifestation alongside the spreadsheets — the numbers hold when the head holds.